


Nothing Smart Glasses Rumors: What IDC's Report Confirms
Reports about Nothing smart glasses surfaced last month, tucked into IDC's quarterly market breakdown under a headline that doubles as the only concrete claim circulating so far: "Nothing Wants to Put Smart Glasses on Your Face, and Two Pairs Could Be on the Way," according to IDC's Q2 2026 analysis. That's the extent of it. No specs, no pricing, no launch window has emerged to back the claim up.
So this isn't a product report. It's a look at whether the market Nothing would be stepping into actually rewards the move IDC describes, and what stands between any challenger and Meta's current lead.
The numbers explain why the speculation lands now rather than earlier this year. Meta's hold on the category runs anywhere from 68.7% to roughly 84%, depending on which tracker and timeframe is used, a gap worth untangling before comparing anything else (IDC, last month; Counterpoint Research, 2 months ago). Display-less glasses alone shipped roughly 2.25 million units in the first quarter of 2026, up 167% year over year and nearly matching all of 2024's volume in a single quarter (IDC, 4 months ago). By the second quarter, growth for the broader XR headsets-and-glasses category cooled to 35.3%, which IDC attributes to tougher year-over-year comparisons and a lull between product cycles rather than any drop in consumer interest (IDC, last month).
What the Nothing smart glasses rumor does and does not confirm
Strip away the headline and what remains is market analysis, not a sourced product leak. IDC's report covers category trends, shipment splits, and competitive dynamics. Neither IDC nor Counterpoint's data independently verifies product names, hardware details, or a timeline tied to Nothing specifically.
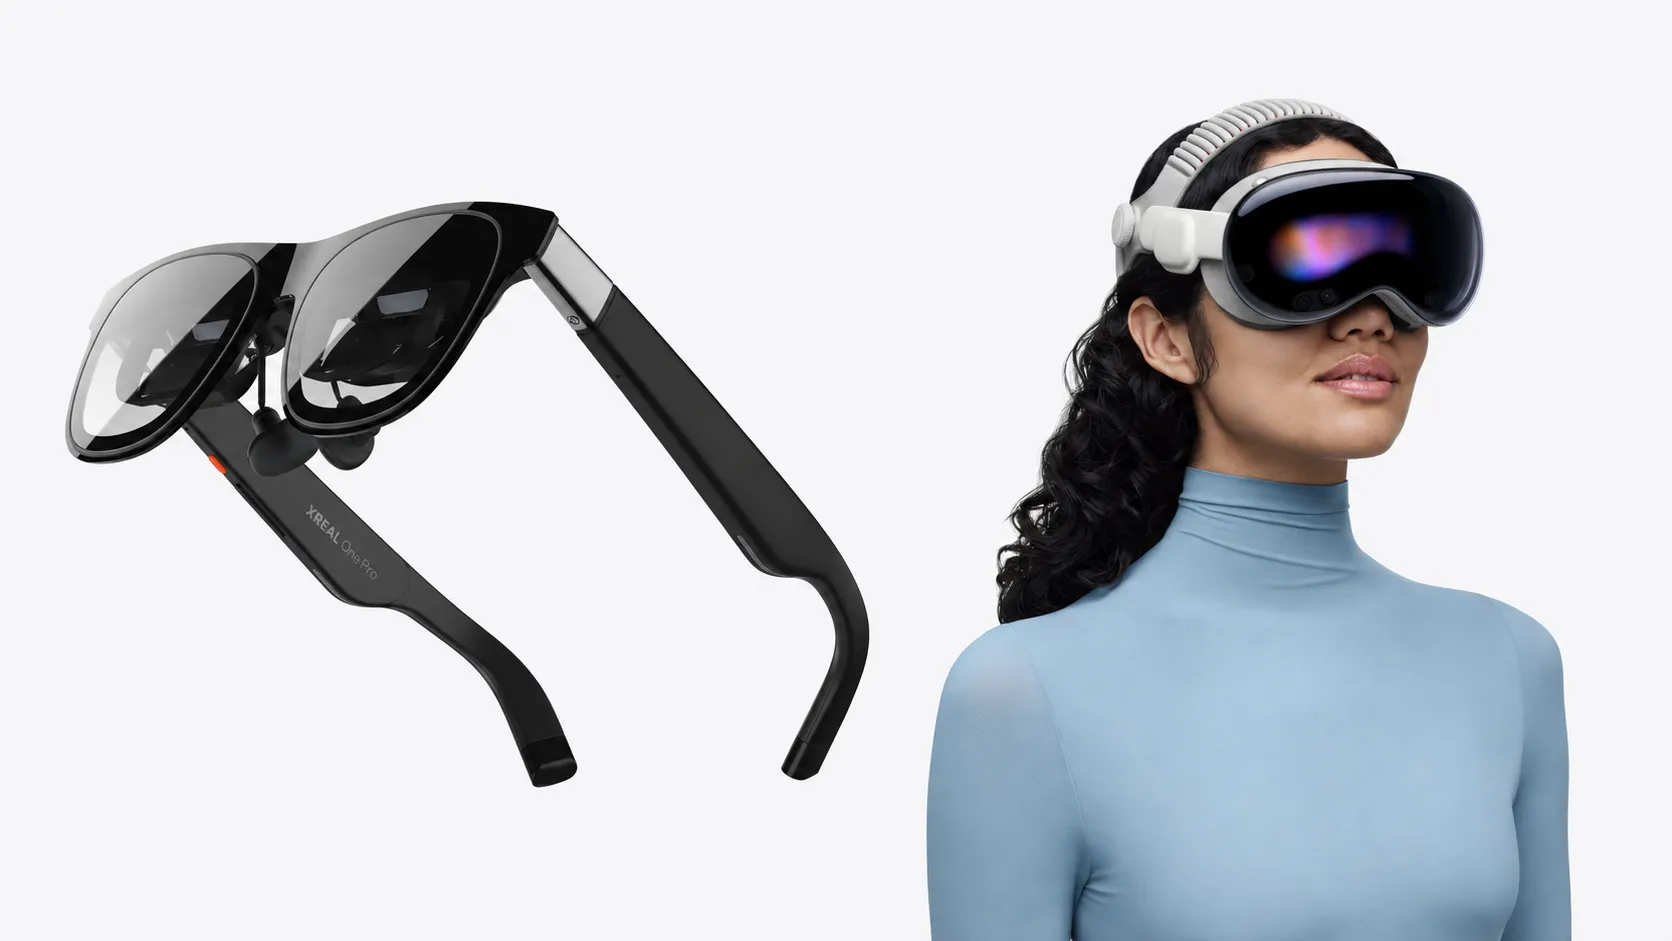
The timing lines up with something concrete, though. IDC's Q2 note points to an active product-cycle window, with Snap, Samsung, XREAL, and Meta itself all expected to introduce new hardware later this year (IDC, last month). That's the backdrop a report naming a would-be challenger showed up against, however loosely sourced the claim itself remains.
IDC also makes the case that glasses have moved past the pilot stage: people are wearing them day to day now, not just trying them at a demo table, which changes who might plausibly want in (IDC, last month). Market data is solid ground here; specific claims about Nothing are not. The two stay separate for the rest of this piece.
A market splitting into two tiers, not a free-for-all
The growth numbers describe a category, not a single market. Audio glasses, the display-less style that includes Ray-Ban Meta, accounted for 70.3% of second-quarter shipments, up from 61.9% a year earlier, making them the clear mass-market layer (IDC, last month).
Display glasses are smaller in volume but growing faster. They held 14.3% share of second-quarter shipments and are forecast to climb from 3 million units in 2026 to 12.2 million by 2030, a 41.9% compound annual growth rate (IDC, 4 months ago). That's a different buyer, a different price point, and a harder design problem than the audio tier presents.
None of this means the field is simply open for the taking. Rising memory and component costs have already pushed some XR vendors to delay launches, trim investment, or rework roadmaps in 2026, with VR hit hardest while audio and AR glasses have proven more insulated (Counterpoint Research, 4 months ago). If Nothing is in fact building toward two products, this tiered structure is the logical reason to split across both rather than bet everything on one segment. That's a read of what the market's shape rewards, not confirmation of what Nothing intends to ship.
Why Meta's lead is bigger than its market share
The headline numbers need a footnote before they mean much. IDC's 68.7% figure covers the combined XR headsets-and-glasses market in the second quarter of 2026, while Counterpoint's roughly 84% comes from its smart-glasses-specific shipment tracker for the first half of 2026, a narrower category measured over a different window (IDC, last month; Counterpoint Research, 2 months ago). They aren't measuring the same thing, and treating them as interchangeable overstates how clean Meta's lead looks on paper.
What the lead is built on matters more than the percentage. IDC points to distribution scale, brand recognition, and AI features threaded across Meta's broader product line, advantages that are harder to copy than any single pair of glasses (IDC, last month).
Pricing strategy plays into that too. Tech companies are increasingly partnering with fashion brands for design and manufacturing expertise, but fashion houses tend to run on higher margins than tech firms will accept, since the latter would rather subsidize hardware through subscriptions or advertising to keep users inside their ecosystem. IDC suggests that's likely one reason Meta released some glasses without EssilorLuxottica's branding attached (IDC, last month).
Everyone else is still playing catch-up at a much smaller scale. In IDC's second-quarter count, RayNeo held 3.6% share and Alibaba 2.6%, a clear sign of how fragmented and under-built the field remains outside of Meta (IDC, last month).
What a Nothing smart glasses strategy would have to get right
Price bands in this category are already set, which leaves little room to improvise. Display-less glasses average around $376 today and are forecast to fall toward $229 by 2030, while display glasses run $516 to $547 on average, with the most capable models priced well above $1,000 (IDC, 4 months ago). An entrant pricing above or below those bands is making a deliberate bet, not finding a gap nobody noticed.
Privacy remains a more open lane. Meta took steps to curb misuse of its glasses only after public backlash over always-on recording, according to IDC, which leaves space for a competitor that builds safeguards in from the start instead of bolting them on after a headline forces the issue (IDC, last month).
Cost pressure cuts the other way. The same component-price inflation that has forced delays and roadmap changes across the industry in 2026 applies to any new entrant as much as it does to an incumbent (Counterpoint Research, 4 months ago). None of this confirms what Nothing will do. It does describe the terms any entrant, Nothing included, would be negotiating with before a single unit ships.
Set against that backdrop, the opening Meta has actually left looks narrower than "better specs." It runs through distribution reach, subscription-subsidized pricing, and how quickly a challenger can earn trust on privacy, the specific areas the data above ties to Meta's advantage rather than to hardware alone.
What comes next
The clearest test of all this arrives with Meta's own Connect event, where the company is expected to introduce a more premium mixed reality headset alongside new display and audio glasses aimed at a more accessible price point (IDC, last month). Snap is preparing to launch its Specs with genuine AR capability, and Samsung and XREAL both have Android XR hardware on the way, the same wave of launches IDC expects to reignite growth after the second quarter's slower pace (IDC, last month).
Nothing's plans, if they exist in the shape IDC's headline suggests, will have to clear that same crowded field. Until independent reporting confirms specifics, the fair way to read "two pairs" is as a strategy the market's current shape makes plausible, not one any company has actually announced.

Comments
Be the first, drop a comment!